Commission reconciliation for Hong Kong insurance brokers after the 2026 commission-spreading rule
- Reconcile each insurer's commission statement against your own policy register every period, not just at year end.
- From 1 January 2026, an IA Practice Note requires that no more than 70% of total commission on participating policies with regular premiums is paid in the first policy year.
- The remainder is spread evenly over at least 5 years or the premium payment term, whichever is shorter, so brokers now track expected commission over several years.
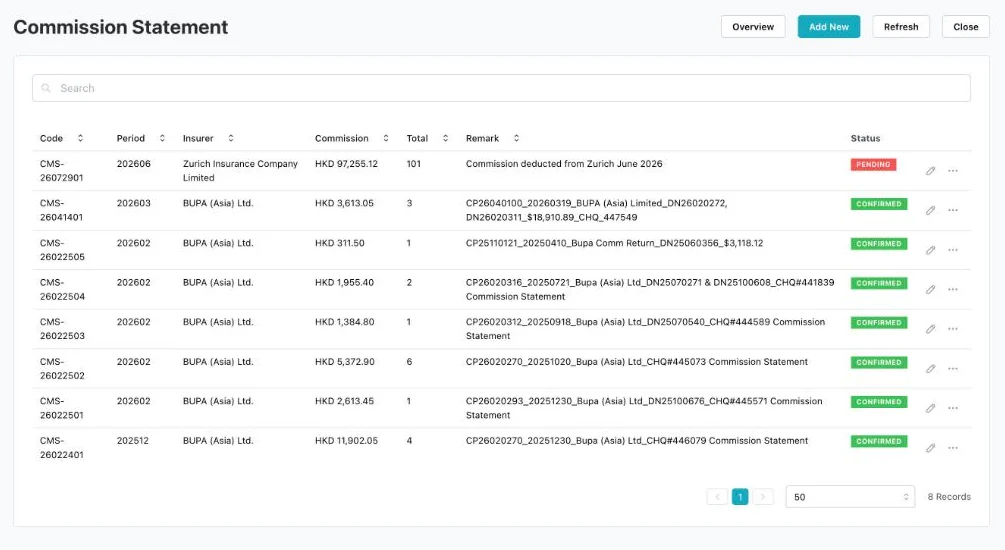
- Mark each statement Pending until it matches, then Confirmed.
What commission reconciliation means for a broker
A broker company earns commission from each insurer it places business with. Each insurer sends commission statements for a period, in its own layout. Reconciliation means checking every line on that statement against the broker's own record of the policy, the premium paid and the agreed commission rate, then resolving the differences before the money is booked.
When the policy register and commission statements live in different places, reconciliation turns into a manual matching exercise every month, and errors carry forward unnoticed.
What changed in 2026: commission spreading for participating policies
On 30 July 2025 the Insurance Authority issued a Practice Note on remuneration structures for participating policies, effective 1 January 2026. For participating policies with regular premium payment terms:
- no more than 70% of the total commission payable may be paid to the intermediary in the first policy year; and
- the remaining commission must be paid over at least 5 years or the premium payment term, whichever is shorter, spread evenly over that period.
The requirement applies to all types of licensed insurance intermediaries, including insurance broker companies. The IA encourages insurers to go further, by paying less than 70% upfront or spreading the rest over a longer period. The Practice Note also sets out exceptions, for example where the policyholder is a professional investor and certain conditions are met.
A worked example
Take a participating policy with a 10-year premium payment term and total commission of HK$10,000 payable to the broker.
| Policy year | Maximum / scheduled commission (HK$) |
|---|---|
| Year 1 | 7,000 |
| Years 2 to 6 (5 years, evenly) | 600 each |
| Total | 10,000 |
The broker now has to track commission it expects to receive over six years for a single policy, and check each year's statement against that schedule. Lapses and surrenders in later years change what is still due. This is hard to follow in a spreadsheet once the book reaches hundreds of policies.
Example for illustration only. Actual schedules depend on each insurer's terms and the Practice Note's exceptions.
A monthly reconciliation process
- Log the statement by insurer and period as soon as it arrives. Status: Pending.
- Match each line to a policy in the register by policy number, client and premium.
- Check the rate and schedule. For participating policies, confirm the amount matches the expected first-year or later-year instalment.
- List the exceptions: missing policies, rate differences, premiums not yet paid, clawbacks after lapses.
- Raise queries with the insurer and record the answer against the line.
- Confirm the statement once every line is explained, then pass it to accounting.
What to keep on record
- Each statement, by insurer and period, with its status.
- For each policy: premium, commission rate, expected schedule and amounts received to date.
- Notes on every query and how it was resolved.
How MBID supports reconciliation
MBID organises commission statements by insurer and period and marks each one Pending or Confirmed. Because statements sit in the same system as the policy register, the finance team can check commission against each order, insurer and consultant. The report centre includes accounting and finance reports drawn from the same data.
Frequently asked questions
What is the IA's 70% commission rule?
An IA Practice Note effective 1 January 2026 requires that, for participating policies with regular premiums, no more than 70% of total commission is paid to the intermediary in the first policy year. The rest is spread evenly over at least 5 years or the premium payment term, whichever is shorter.
Does the commission-spreading rule apply to broker companies?
Yes. The requirement applies to all types of licensed insurance intermediaries, including individual agents, insurance agencies and insurance broker companies, subject to the exceptions in the Practice Note.
How often should a broker reconcile commission statements?
Every statement period, as each insurer's statement arrives, rather than only at year end.
Sources
This article is general information for insurance professionals and is not legal or regulatory advice. Check the Insurance Authority's current guidelines for your circumstances.